“Quick answerHard money lenders use predictive analytics to price collateral before an appraisal comes back. Five platforms cover the work in 2026. Homesage.ai reads property condition from photographs and prices the renovation. ATTOM supplies the public records. Clear Capital supplies a lending-grade valuation. Cotality covers risk and MLS distribution, and AirDNA validates a short-term rental exit.
Hard money moves faster than an appraisal does. A borrower wants a decision this week, and the report arrives in two.
Freddie Mac puts the median appraisal cost at $450 to $700 and the turnaround at roughly one to two weeks, longer where appraisers are busy. That gap is the whole reason predictive analytics entered this business.
The point is not to replace the appraisal. It is to decide which files deserve one.
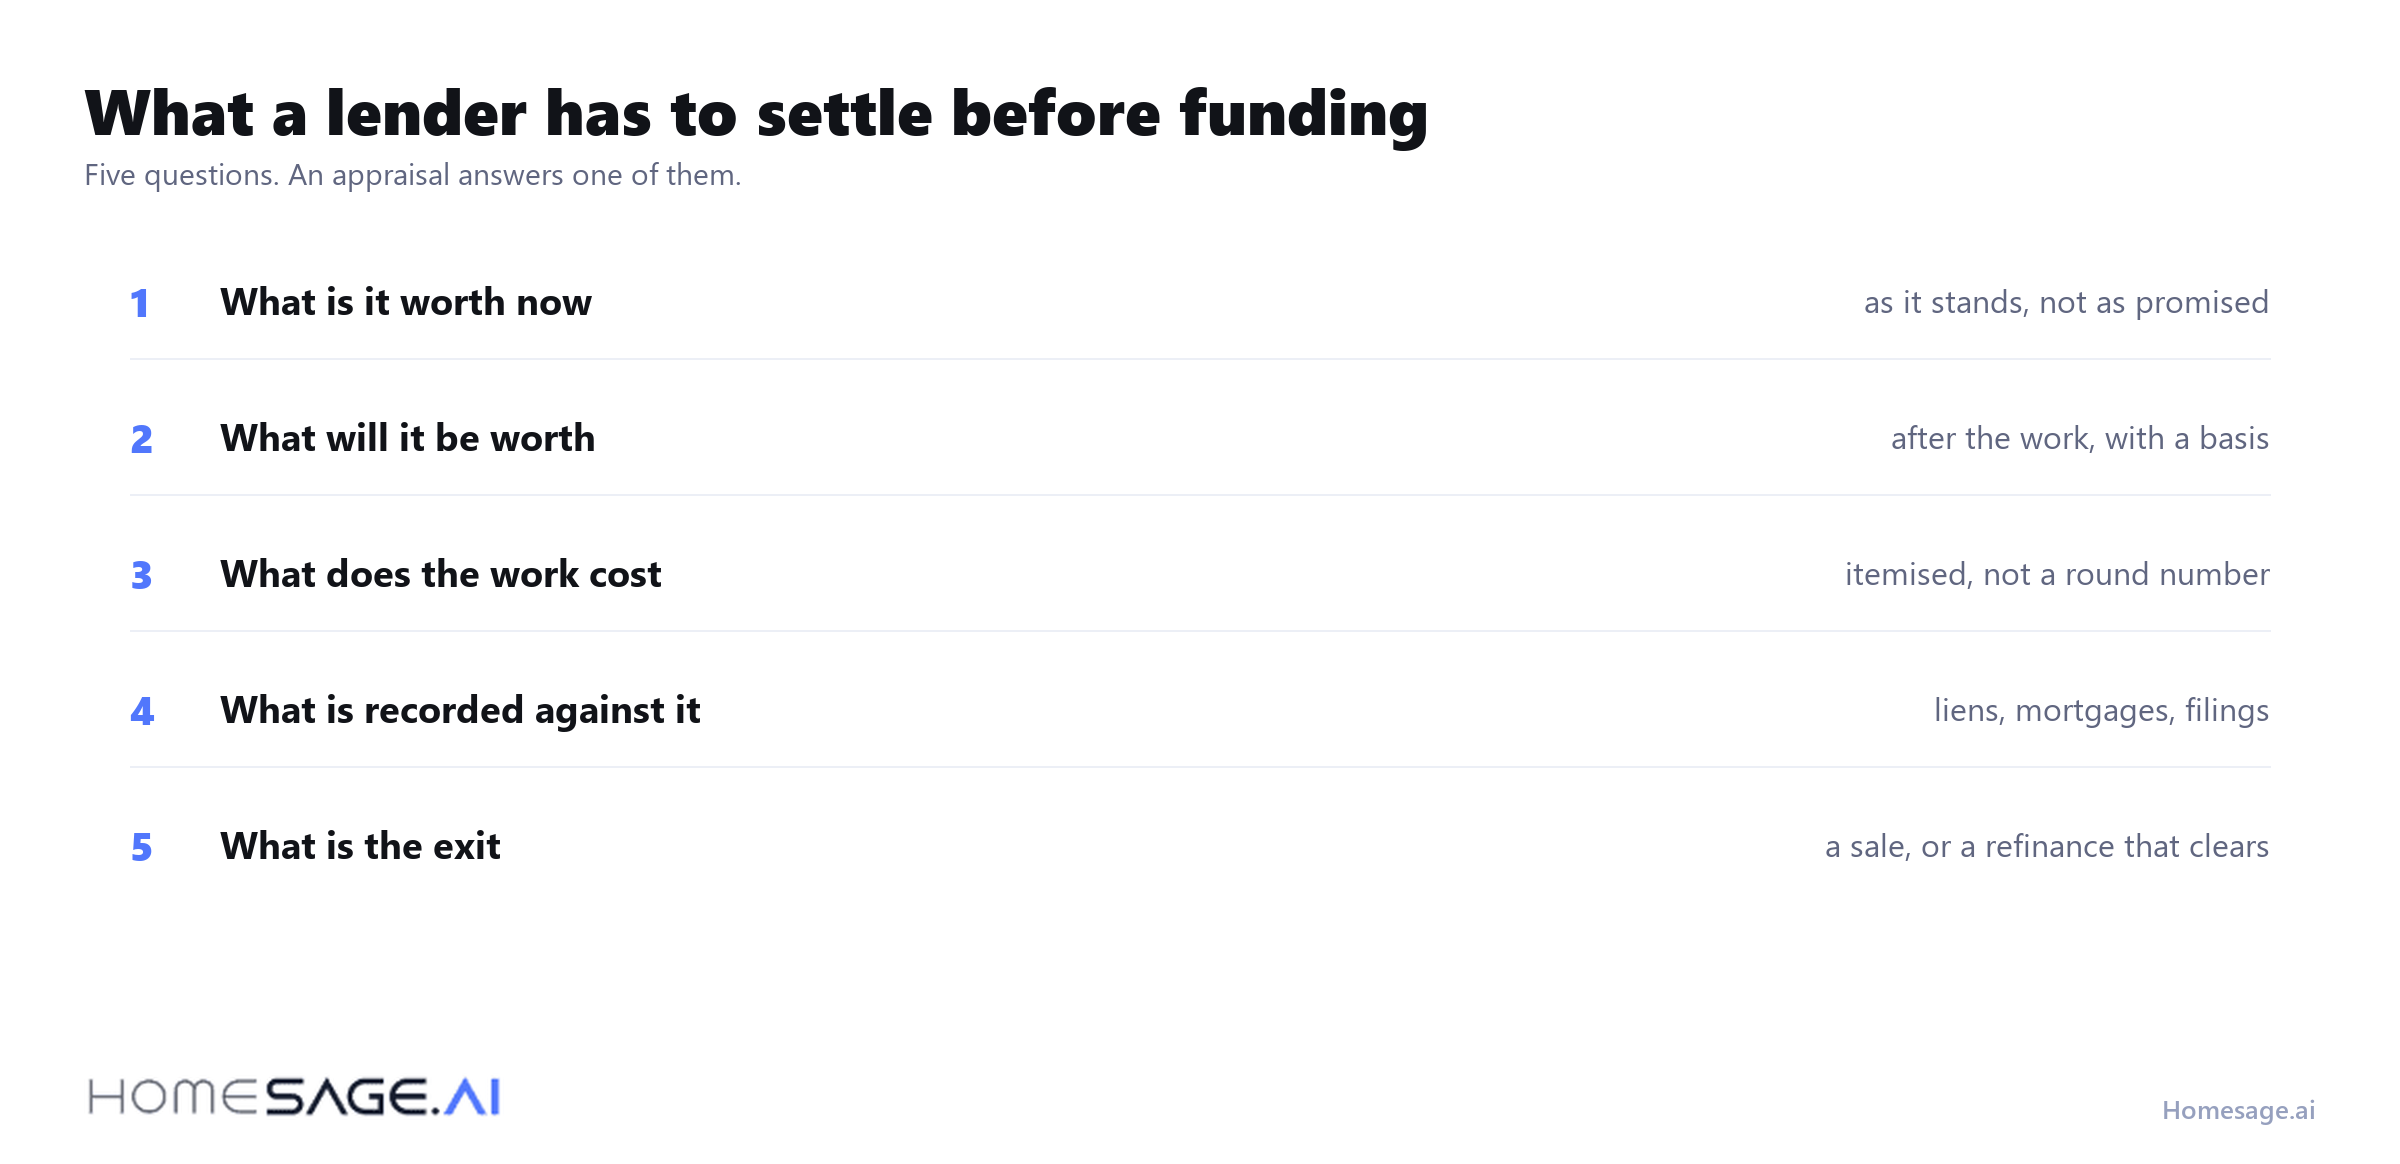
What a lender has to settle before funding
Five questions decide a hard money loan. What is it worth now, and what will it be worth after the work. What does the work cost. What is recorded against the title, and what is the exit.
An appraisal answers the first one well and the others barely. The rest is what the analytics layer is for.
How few renovation deals actually clear the bar
Lenders tend to screen on property condition, because distress is what brings the borrower through the door. Condition on its own is a poor filter.
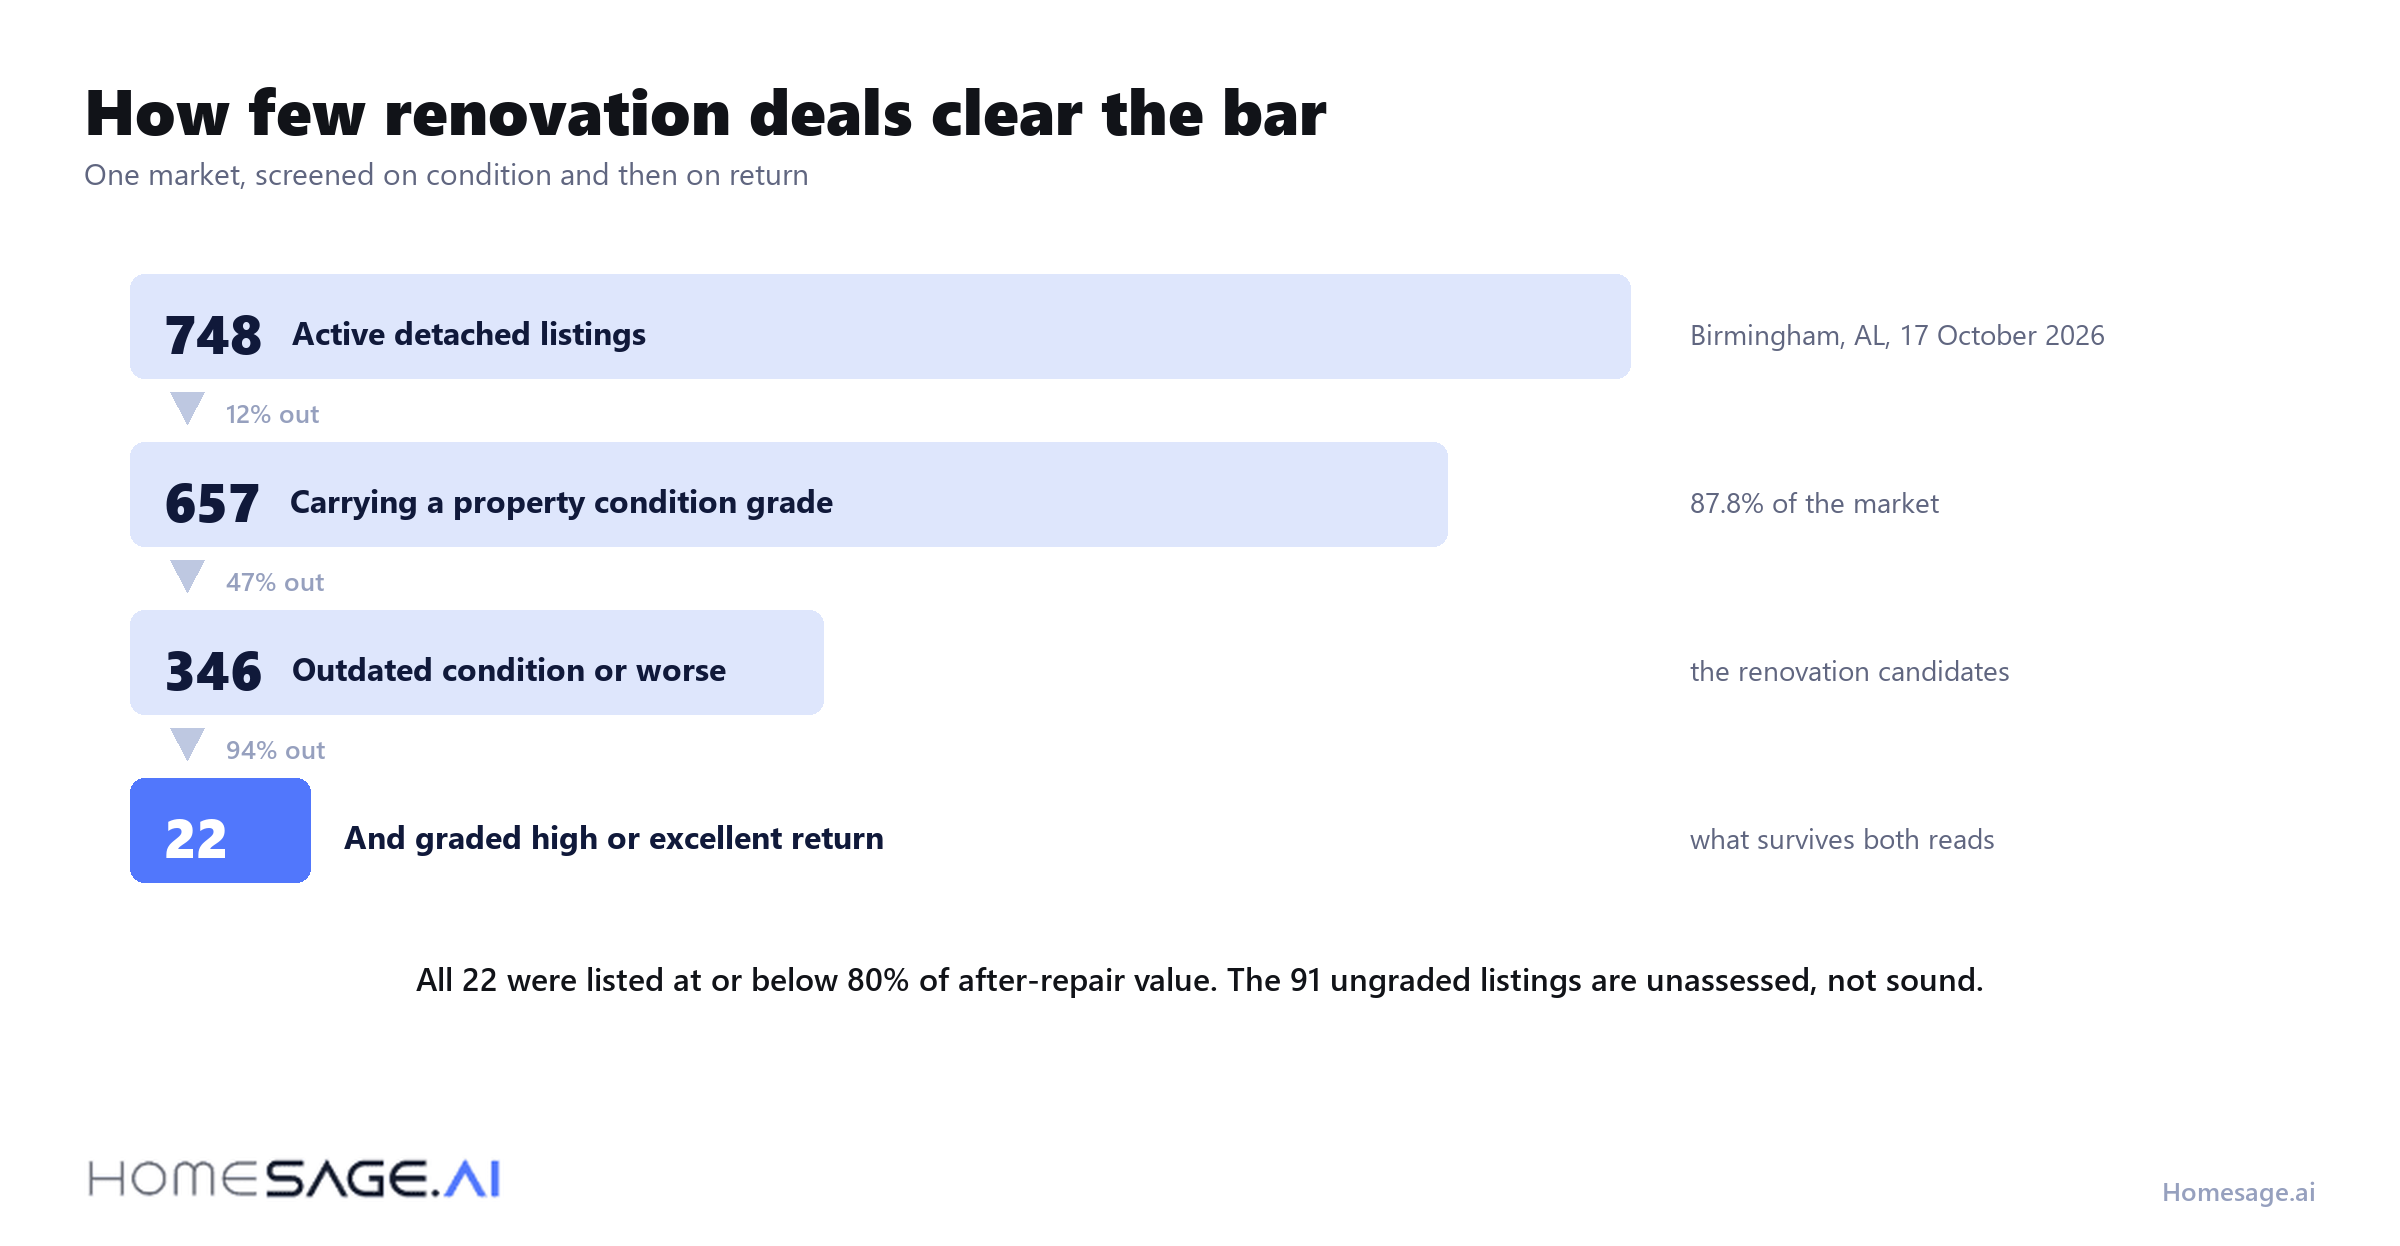
We screened one market both ways. Birmingham, Alabama, active detached listings, 17 October 2026.
| Birmingham screen | Listings | Share of the market |
|---|---|---|
| All active detached listings | 748 | 100% |
| Carrying a property condition grade | 657 | 87.8% |
| Property condition outdated or worse | 346 | 52.7% of the graded |
| Graded high or excellent return | 50 | 6.7% |
| Both condition and return | 22 | 2.9% |
Homesage.ai property database, Birmingham active detached listings, 17 October 2026. 657 of the 748 carry a property condition grade, which is 87.8%, so the condition rows are shares of those 657. Every listing carries a return grade. All 22 were listed at or below 80% of their after-repair value. Counts move daily.
346 of the 657 graded houses look like renovation deals. 22 of them survive a return check as well. A lender screening on property condition alone carries the other 324 into underwriting and pays for the discovery later.
Speed is not the advantage people think it is. The advantage is rejecting the wrong file before anyone has paid for an appraisal on it.
The 5 predictive analytics tools lenders use
1. Homesage.ai. Best for pricing the work behind the loan
Our platform is built for the part of the file that an appraisal does not cover. It grades the property condition from listing photographs, estimates the renovation cost, projects the after-repair value and scores the return.
For a lender the useful output is the combination. A property condition grade on its own is a description. Set against a renovation cost and an estimated ARV, it becomes a loan-to-value you can defend.
The Seller Motivation Score adds the negotiating room on the purchase side, which tells you whether the borrower’s entry price is realistic. All of it is available through our real estate APIs, so it can run inside an existing loan origination system.
Best for: fix-and-flip and bridge underwriting, and any file where the renovation drives the risk.
2. ATTOM. Best for the public record behind the title
ATTOM states coverage of more than 160 million US properties, drawn from assessors and recorder offices. Transaction history, tax records, lien information and foreclosure data all sit in one normalised schema.
For distressed lending this is the depth that matters. If a property has a complicated past, ATTOM is where that past is written down.
Best for: distressed and complex-title lending, and portfolio risk review.
3. Clear Capital. Best for a lending-grade valuation
Clear Capital describes ClearAVM as a lending-grade automated valuation model with nationwide coverage. It also sells the appraisal review products that sit around a valuation, including Collateral Desktop Analysis.
The reason it belongs on a lender’s list rather than an investor’s is the review layer. When a number has to survive a credit committee, an AVM built for that purpose is a different product from one built for a consumer.
Best for: lenders who need a valuation and its review from the same source.
4. Cotality. Best for risk data and MLS distribution
Cotality is the business that traded as CoreLogic until its rebrand on 24 March 2025. Vendor lists across the industry still say CoreLogic, and it is the same company.
Its coverage runs to valuations, lien data, flood and climate risk and market analytics. Trestle, the MLS data distribution product, keeps its name and is certified against the RESO Data Dictionary.
Best for: lenders who also originate conventional mortgages or report to institutional capital partners.
5. AirDNA. Best for validating a short-term rental exit
When the borrower’s exit is a short-term rental, the question is whether the projected income supports a refinance. AirDNA’s Rentalizer projects annual revenue, average daily rate and occupancy for an address from nearby comparable listings, with a confidence score on the comparable set.
AirDNA offers an enterprise API for lenders who want this inside their own workflow rather than as an exported report. The 7 best property data APIs compares the feeds underneath.
Best for: bridge loans where the exit is a short-term rental rather than a sale.
Screening the title before the file moves
The fourth question is the one that kills deals late. What is recorded against the property, and does any of it outrank your lien.
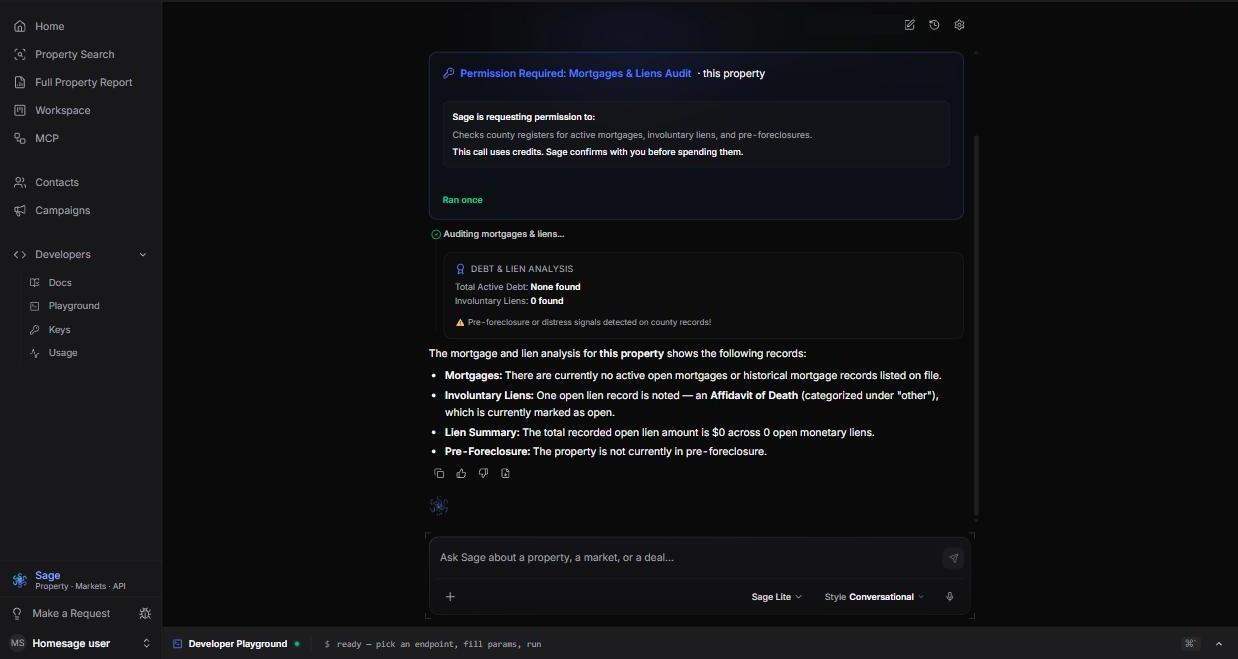
Running that check at screening rather than at closing is the cheapest process change available to a small lending desk.
How the five compare
| Platform | Core strength | Reads property condition | Prices renovation | Built for |
|---|---|---|---|---|
| Homesage.ai | Condition, renovation cost, ARV and return | Yes | Yes | Fix-and-flip and bridge |
| ATTOM | Public records depth and foreclosure history | No | No | Distressed and complex title |
| Clear Capital | Lending-grade AVM and appraisal review | Inspection products | No | Credit committee defensibility |
| Cotality | Risk data and MLS distribution | No | No | Conventional and institutional |
| AirDNA | Short-term rental revenue projection | No | No | Rental exit validation |
Published capabilities, checked 17 October 2026.
How to choose a data feed
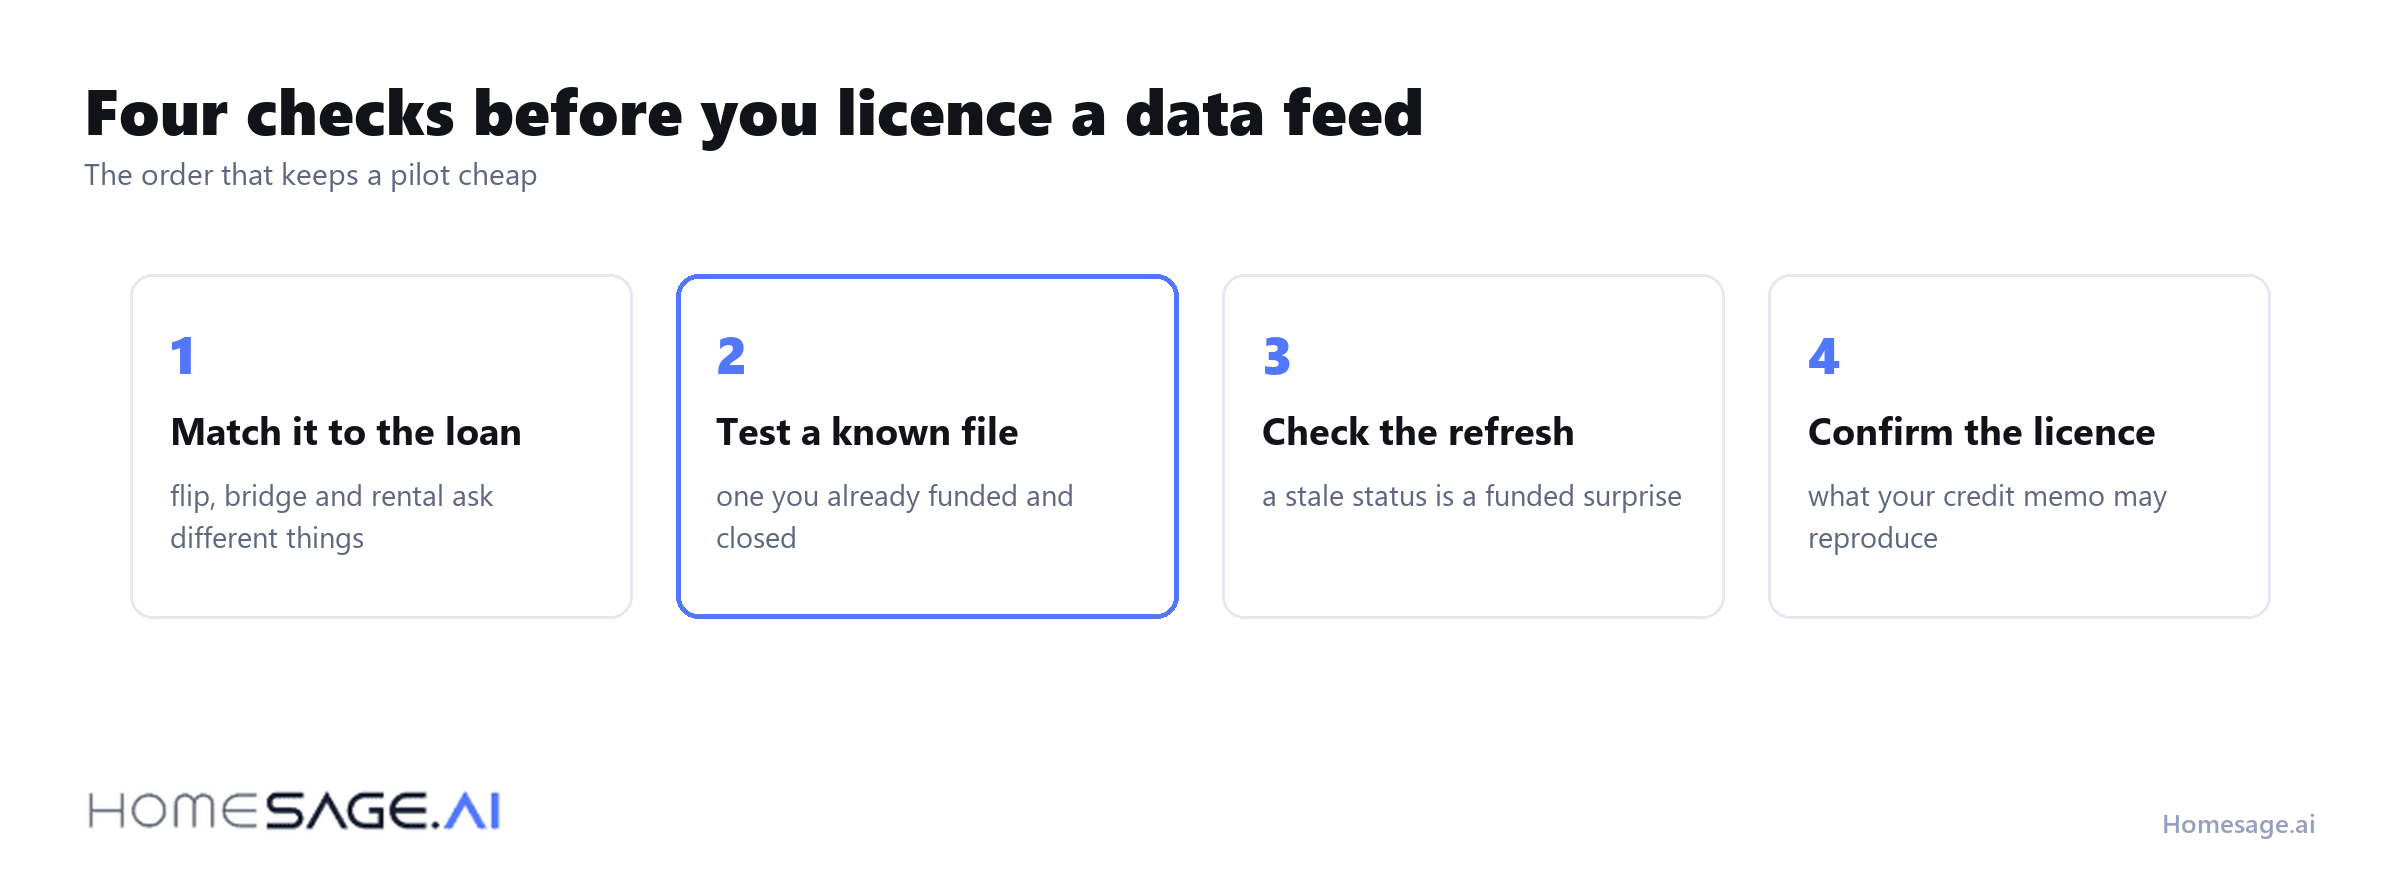
Match the feed to the loan type first. A flip desk and a rental desk are buying different products even when the brochure looks the same.
Then test it on a file you already closed. You know the outcome, so you can measure the tool rather than trust it. Our guide to AI for hard money lenders covers the wider workflow, and renovation cost estimating tools goes deeper on the repair line.
Key takeaways
- Analytics do not replace the appraisal. They decide which files are worth paying to appraise, against a median cost of $450 to $700 and a one to two week wait.
- Property condition alone is a weak filter. In Birmingham on 17 October 2026, 346 of the 657 graded listings looked like renovation deals and 22 also cleared a return bar.
- Screen the title early. Mortgages, involuntary liens and pre-foreclosure filings are cheap to check at screening and expensive to find at closing.
- Match the feed to the loan. Flip, bridge and rental exits each need a different primary source.
- Check your vendor list for stale names. CoreLogic has traded as Cotality since 24 March 2025.
Conclusion
Hard money has always been collateral lending. What has changed is how much of the collateral you can read before committing capital.
Condition, repair cost, after-repair value and recorded debt are all available in minutes. A desk that reads them at screening funds fewer bad files and loses fewer good borrowers to a faster competitor.
The analytics are not the edge. Using them to say no early is.
Frequently asked questions
Can predictive analytics replace an appraisal for a hard money loan?
No. They screen and prioritise. Most lenders still order an appraisal for files above a set threshold, and use analytics to decide which files reach that stage.
What does an appraisal cost and how long does it take?
Freddie Mac puts the median cost at $450 to $700 and the turnaround at roughly one to two weeks from inspection to final report. Busy markets run longer.
How accurate are automated valuations for lending?
Accuracy varies by market and by comparable coverage, and vendors measure it differently. Treat any single accuracy claim with caution and test a model on files you have already closed.
What should a small lending desk buy first?
The layer covering repair cost and after-repair value, because that is where fix-and-flip risk concentrates. Public records depth is the usual second purchase.
Sources
- Freddie Mac, What homebuyers can expect at the appraisal, last reviewed 21 October 2025.
- ATTOM, property data coverage, checked 17 October 2026.
- Cotality, CoreLogic global rebrand announcement, published 24 March 2025.
- Clear Capital, ClearAVM, checked 17 October 2026.
- Homesage.ai property database, Birmingham active detached listings, 17 October 2026.
Estimated values, ARV, renovation costs and return scores are model-derived estimates, not lending advice or an appraisal. Property data as of 17 October 2026.


Peter February 4, 2026
Modern AI powered tools are necessary for lenders
Robin February 4, 2026
great read!
Mia February 4, 2026
Very helpful!
Emi February 4, 2026
Very insightful!
Property Data API Guide: 7 Best Picks For Developers October 18, 2026
[…] still carries the Trestle name and remains the route most platforms take to licensed listing data. The 5 predictive analytics tools lenders use shows the same stack inside a lending […]